The Homebuyer's
Guide.
Everything I walk my buyers through, in one place: how we start, which loan fits, the paperwork, the 18 steps from application to keys, and how to protect your approval on the way.
 Text Ashley
 Book a Call
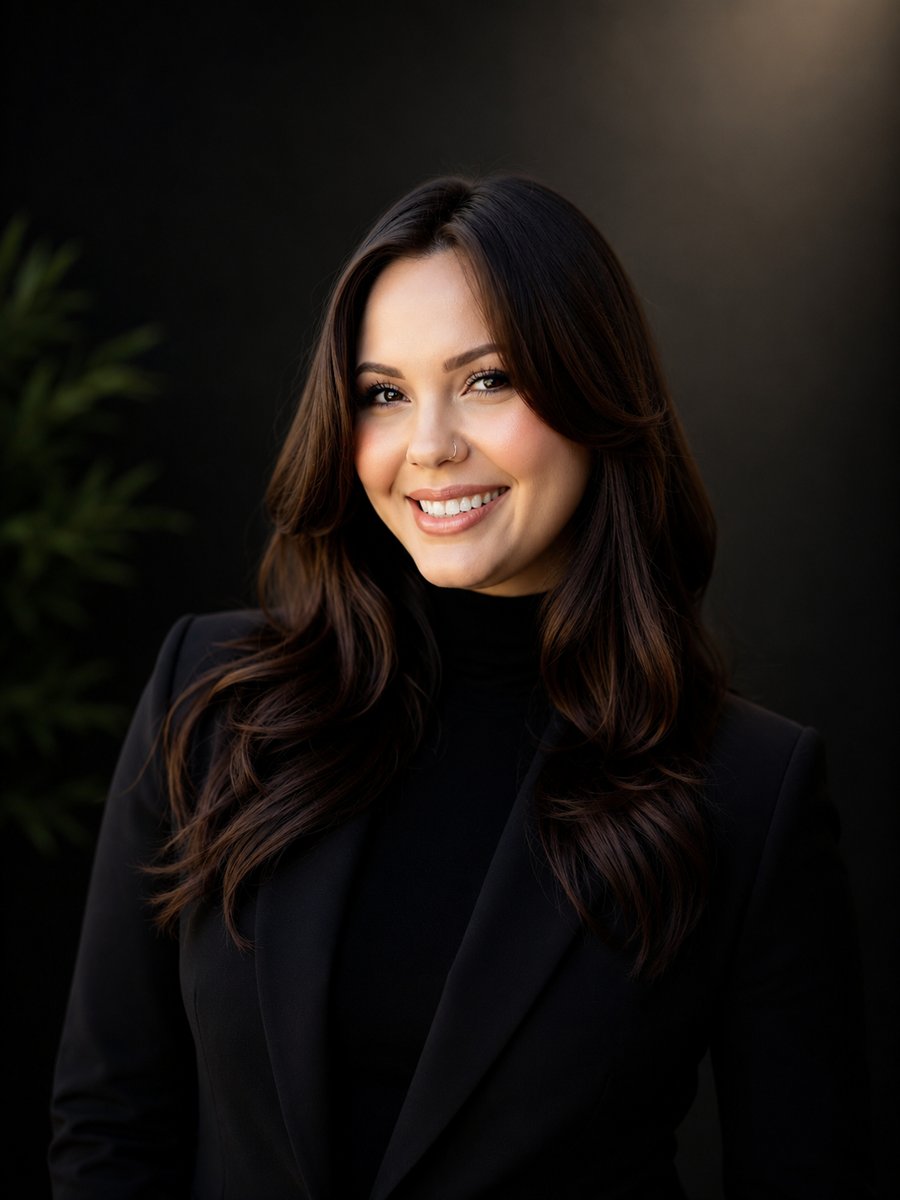
A relationship first, not a file number.
I've spent over 15 years in finance, and I stay with you from the first conversation through closing, and long after. Our first call isn't a sales pitch. It's four questions.
Where are you right now?
What have you saved?
What payment would feel comfortable?
What do the next few years look like?
You leave with a plan, even if the plan is "not yet."
Tell me your scenario
No credit pull, no obligation.
We map your options
A call so I understand the full picture.
Get pre-approved
Ready to make offers with confidence.
Go from there
Clear updates from application to keys.
Whatever you're financing, there's a structure for it.
 Flexible credit
FHA
Lower down payments and flexible credit qualifying for your first home.
 Most popular
Conventional Fixed
One locked rate, one predictable payment, for the life of the loan.
 Veterans
VA
No down payment and exclusive benefits for those who served.
 High value
Jumbo
Competitive financing above conventional loan limits.
 Buy + renovate
FHA 203k / HomeStyle
Roll the purchase and the remodel into a single loan.
 Investors
DSCR
Qualify off the property's rental income, not your W-2.
 Homeowners
HELOC
Tap the equity you've built without touching your first mortgage.
 Most requested
Creative & Non-QM
Bank statement, 1099, asset-based and multi-property income.
Down payment help exists.
Programs like CalHFA and GSFA can help cover part of your down payment and closing costs, often as a second loan alongside your first mortgage. Availability depends on income limits, property location and program funding, so it's worth checking every time.
 See Your Estimated Payment →
Debt to income, in human words.
Car payment, student loans, card minimums and your future house payment all count. Lenders use this to decide how much payment you can comfortably carry.
Have these ready and you'll close faster.
Having them ready before they're requested is the single fastest way to speed up your closing.
 Upload Through My Portal
Upload through your portal. Never email bank statements or IDs.
- Two most recent pay stubs
- W-2s for the last two years
- Federal tax returns, last two years (all pages)
- Two most recent bank statements (all pages)
- Retirement or investment account statements
- Government-issued photo ID
- Employer name, address and contact
- List of monthly debts and obligations
- Documentation for any additional income
- Rental history (if applicable)
- Explanations for unusual deposits or credit inquiries
- Self-employed: 12 to 24 months of business bank statements or a YTD P&L
Application to keys,
in 18 steps.
Pink steps are your turn. Everything else happens behind the scenes. Tap any number to jump to that step.
- 01
Application
You complete the online application
- 02
Document requestYour turn
Upload what's on the list
- 03
Pre-approval
Letter issued, you're ready to make offers
- 04
Escrow opened
Offer accepted, contract in hand
- 05
Updated document requestYour turn
Property-specific items
- 06
Disclosures sentYour turn
E-sign in the portal
- 07
Appraisal ordered
Value and condition review
- 08
Submitted to processing
File assembled and checked
- 09
Submitted to underwriting
Formal eligibility review
- 10
Conditional approval
Approved, pending a short list of items
- 11
Conditions collected & submittedYour turn
Clear any remaining items
- 12
Clear to close
Underwriting is finished
- 13
Loan docs ordered
Final paperwork prepared
- 14
Docs sent to escrow
Signing appointment scheduled
- 15
SigningYour turn
Sign with escrow
- 16
Final document request
Any last items from signing
- 17
Funding review
Final quality check
- 18
Clear conditions & fundKeys 🔑
Funds released, deed records, keys
What not to do before closing.
Your approval is a snapshot of your finances. Changing the picture, even a little, can delay closing. When in doubt, text me first.
- Open new credit cards or lines of credit
- Finance furniture, appliances, or a vehicle
- Make large or unexplained deposits
- Move money between accounts without telling me first
- Change jobs or employment status without telling me
- Miss a payment on any existing account
- Co-sign for someone else's loan
- Assume a financial change is too small to mention
Wire fraud targets homebuyers in the final days before closing.
Criminals send emails that look exactly like they came from escrow, title, your agent, or me.
- Wiring instructions never change at the last minute. If you get "updated" instructions, assume fraud.
- Call escrow at a number you already had, not one from the email, and confirm the details verbally.
- I will never send you wiring instructions or ask you to wire money to me. Neither will Cornerstone.
- Something feels off? Stop and call me at (510) 314-9000. A wired down payment is unrecoverable.
Underwriter shorthand, translated.
- Conditional approval
- You're approved. The underwriter just needs a few specific items before it becomes final.
- LOE (letter of explanation)
- A short, signed note explaining something on your file: a deposit, a credit inquiry, a gap in employment. Three sentences is usually plenty.
- Sourced & seasoned funds
- Underwriting needs to see where a deposit came from (sourced) and that it's been in your account long enough (seasoned), usually 60 days.
- VOE (verification of employment)
- We confirm your job directly with your employer. This happens at approval and again just before funding.
- Gift letter
- If a family member is giving you money for the down payment, they sign a letter confirming it's a gift, not a loan.
- PTD vs PTF
- Prior-to-doc conditions must clear before loan documents are drawn. Prior-to-funding conditions clear after you sign, right before money moves.
- Clear to close (CTC)
- Every condition is satisfied. Underwriting is done and closing documents can be prepared.
- Rate lock
- Your interest rate is guaranteed for a set window (typically 30 to 45 days). Closing delays past the lock expiration can cost money.
Every one of these started where you are.
"She made the process of purchasing my first home such a smooth process."Sergio B. · Google
"Ashley treated me like family since day one, making me feel safe and understood."Adelina C. · Patterson, CA
"Professional, knowledgeable, and always available to answer my questions."Cesar P. · Oakland, CA
Let's map out your plan.
Want a copy?